
Remember back in May when we told you Garmin was printing money? Well, the machine hasn’t jammed.
Garmin reported its third quarter and it was another record: $1.99 billion in revenue, up 12% from last year.
Earnings came in at $2.76 a share, comfortably ahead of the roughly $2.38 Wall Street was expecting. Then Garmin raised its full-year forecast to about $8.15 billion in revenue and $10.80 a share. For context, it started the year guiding to about $7.9 billion and $9.35. And with that, shares ticked up about 3%. Not bad!
Garmin is on fire and whose to say it ever stops. They make the watch on your wrist, the bike computer on your stem, and now own the platform where your coach writes your plan. Incredibly savvy and its bank account tells you a lot about where your training life is headed.
Breaking It Down
The Fitness division, which is where your Forerunner lives, brought in $694 million, up 16% and a Q3 record.
Then Outdoor jumped 20% to $597 million. That’s the fēnix side of the house, and it spent the first half of the year in the doghouse, down 5% in Q1 and 2% in Q2. Then the fēnix 9 showed up and everything flipped. Outdoor made $233 million in operating income, a touch more than Fitness made.
If you remember, we pointed out that the fēnix 9 got a lot more expensive but nobody seems to care as Garmin’s CEO, Cliff Pemble says early demand has been especially strong from existing owners upgrading from older generations. So regardless of the economy or whatever, people looked at the price tag, sighed, and tapped buy anyway.
The rest of the lineup was no slouch, either.
Marine grew, Aviation grew. The lone weak spot was car stuff, with Auto OEM down 20% to $132 million, though Pemble says a big Mercedes-Benz program should turn that around in 2027.
Gross margin climbed 420 basis points to 63.3%, and operating income jumped 34% to $612 million.
What about CIRQA?
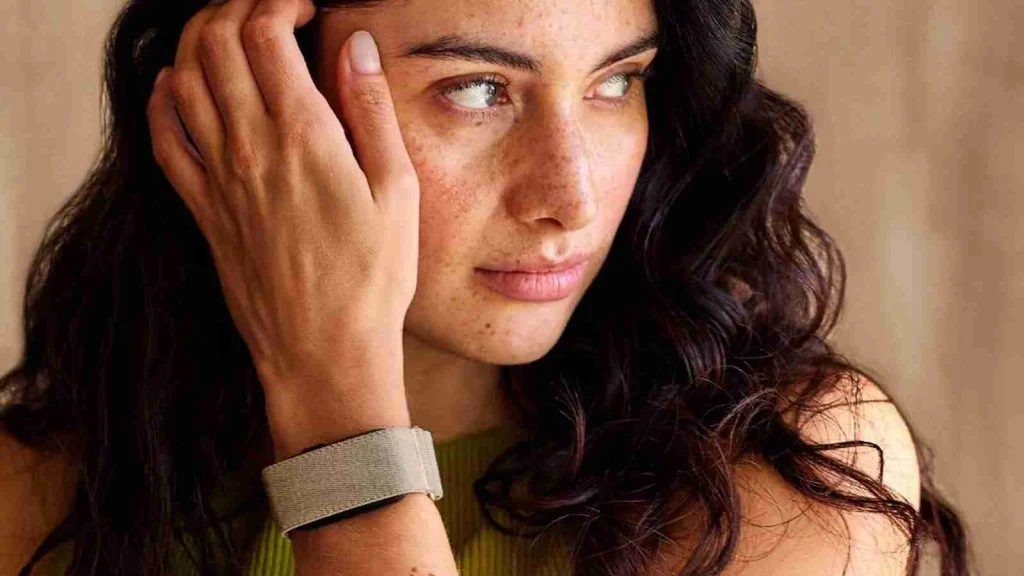
In July we asked whether the CIRQA was too late to the screenless band party and Garmin says, nahhhh, you wring.
Demand blew past its own expectations and it’s still working through a backlog. Pemble also said CIRQA buyers are signing up for Connect+, Garmin’s subscription, which has been growing faster than the product lines behind it.
Cash Is King, and Garmin Has a Lot of It
Garmin ended the quarter with about $4.1 billion in cash and marketable securities, after generating $394 million in operating cash flow in Q3 alone and still handing shareholders $202 million in dividends and another $41 million in buybacks. That’s ton of capital and they went shopping big time.
In July, Garmin bought TrainingPeaks and TrainHeroic, the two platforms where a huge share of coached endurance athletes and strength coaches keep their training lives. Along with it was about 120 employees, and though the price tag wasn’t disclosed, we can’t imagine it was cheap. On the earnings call, Pemble described it as closing a loop: your device records the training, TrainingPeaks puts it in front of a coach, and the coach’s guidance feeds your next plan.
And the hardware announcements didn’t slow down either.
Since July, Garmin has dropped the Tacx NEO 2T with a Zwift cog pre-installed, the Enduro 4 with its 90 days of battery life, the Edge 1060 with “Okay, Garmin” voice control, the Edge Explore 3 and Explore 3 Plus, and a wobbling $1K Tacx Nēra.
That’s two watches, a band, two trainers, three bike computers, and two training platforms in about three months. Most companies don’t announce that much new hardware in two years.
Rough Seas Ahead?
While it is mostly all good news, fitness growth has cooled, from 42% in Q1 to 25% in Q2 to 16% in Q3. They’re still strong, but if we do want to nit pick, it’s a trend line.
Garmin also got a boost from about $33 million in refunds of previously paid tariffs, so not all of that profit came from selling watches. And Pemble said gross margins should settle back to their historical range in 2027, mostly because memory chips are getting pricier.
Back in May we told you to budget for possible price hikes next year and the CEO is saying as much. Things are not getting cheaper and Black Friday holiday deals may be the time to buy.
Pemble’s counter is that registrations outpaced sales to retailers, meaning shops ran lean heading into the holidays while real athletes kept buying. We’ll see how Q4 shakes out.
Our Thoughts
Garmin is flush, confident, and quite clearly building a full ecosystem around you: the watch, the band, the trainer, the bike computer, the coach, the plan.
Garmin just doesn’t need to screw up whats already working and they’ll continue to see record breaking quarters. Done carelessly and people might start to discuss how its becoming a very comfy walled garden like Apple. TrainingPeaks has told us it plans to keep operating cross-platform, and we’re holding everyone to that.
For now, if you’ve got a watch on your wrist and some holiday money burning a hole in your pocket for a new trainer or something else, purchasing it this holiday season may be the best deal, and best bet that you’re getting it at its cheapest price.
Leave a Reply
You must be logged in to post a comment.