
On had a great quarter. Let me say that clearly before I pick at it.
Third-quarter net sales rose 17.2% to CHF 931.4 million (note – 1 Swiss Franc = $1.21 USD), the first time On has cleared CHF 900 million in a quarter.
Every region posted its best quarter ever, according to the company. It also says it did it without discounting.
That last part is the biggest flex, and it’s the part I want to dig into, along with one big asterisk on the margin stuff.
The Scoreboard
Straight from On’s release, for the three months ended September 30, 2026:
- Net Sales. CHF 931.4 million, up 17.2% (17.8% in constant currency)
- Direct-to-Consumer. up 25.0% to CHF 393.3 million, now 42.2% of sales
- Wholesale. up 12.2% to CHF 538.2 million
- By Region. APAC up 31.1%, EMEA up 17.9% (topping CHF 250 million for the first time), Americas up 12.4%
- By Category. shoes up 15.4% to CHF 843.7 million, apparel up 38.7% to CHF 69.5 million, accessories up 39.2% to CHF 18.1 million
- Gross Margin. 72.6%, up from 65.7%
- Net Income. CHF 162.8 million, up 36.9%
On also kept its full-year outlook for net sales growth in the low-20% range in constant currency, which it says implies CHF 3.47 billion to CHF 3.56 billion at current exchange rates.
How Much of That Margin Is Real?
Now, here’s the asterisk. That 72.6% includes CHF 52.6 million in U.S. tariff refunds.
Take those out and On says gross margin was 66.9%. That’s still very good. It’s also 5.7 points less exciting than the headline number.
For context, my math says CHF 52.6 million is equal to about a third of the quarter’s CHF 162.8 million in net income. That’s a refund doing a lot of heavy lifting in the announcement.
But to be fair to On, it isn’t hiding this.
The company breaks it out right in the summary, and it shows adjusted EBITDA margin both ways: 27.6% with the refunds, 21.9% without. It also says that once you adjust for the refunds and a one-time freight benefit in last year’s quarter, gross margin was up about 320 basis points year over year.
So the underlying business really did get more profitable. Just not 72.6%-profitable.
So if you see that number on social without the context and think holy crap, now you know. Still impressive though.
Full-year guidance follows the same logic. On now expects about 67.5% gross margin including the refunds, or about 66% without them. That’s up from its earlier “at least 65%.” Adjusted EBITDA guidance excluding refunds stays at 19.5% to 20.0%.
Full Price in a Discount World
This is the part I actually find impressive.
Co-CEO Caspar Coppetti said, “In a promotional market, we stayed true to who we are and held full price, delivering record sales and record underlying margins.”
CFO Frank Sluis went further: “premium is not the adjective in our financial model – it is the mechanism.”
And that’s a pretty spicy and bold line. Also a sharp contrast with the rest of the category.
Back in April, when On handed the keys back to its founders, I pointed out how much strain the big players were under at the same moment. Seven months later, On is posting records while saying out loud that it isn’t playing the markdown game.
Whether that holds through the holidays is the real test. On says it’ll run the season “remaining committed to its premium positioning and full price discipline in a promotional environment.”
I’ll believe it when I don’t see Cloudmonsters at 40% off in January.
Runners, Soccer and Zendaya
Now the question I keep coming back to: is On still a running company?
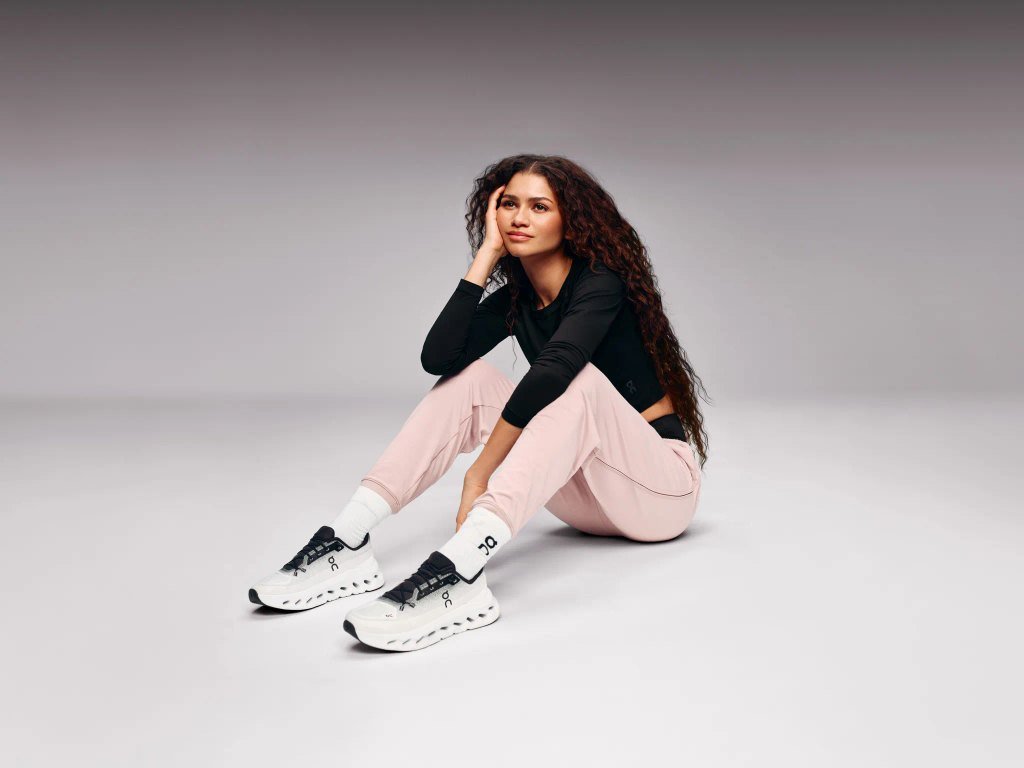
The release lists three growth engines. Performance is “led by Run.” Lifestyle is “led by Sneaker,” with the Cloudtilt called “one of the industry’s fastest-growing sneaker franchises.” Apparel is “led by Her,” with the latest Zendaya collection described as “On’s most visible apparel launch yet.”
On also says its football (soccer) announcement became “the most seen brand moment in its history.”
Here’s my take. Apparel is growing fast, but it’s still small. CHF 69.5 million is about 7.5% of the quarter by my math. Shoes are still about 91% of the business.
And the running proof points are real. The release credits the Cloudsurfer 3 with “strong sell-out in its run specialty pre-launch,” and On’s athletes landed podiums in both the men’s and women’s races in New York, which On calls a first for the brand at a World Marathon Major. I covered that New York result in my Marathon Majors breakdown.
And I also reviewed the Cloudsurfer 3 and called it a yes for the right runner, with some question marks. It’s also the shoe On chose to launch through specialty run stores first so it hasnt even hit their direct sales channel.
So no, I don’t think soccer and celebrity apparel are diluting run specialty yet. The risk is attention, not numbers. Every new sport and every celebrity drop competes for the same R&D, the same marketing dollars and the same shelf space. The day the run specialty store becomes the third priority is the day I’ll worry.
My Thoughts
This was a legitimately strong quarter, and On deserves credit for growing 17% at full price while saying the market is promotional.
But the headline margin needs an asterisk, and I’d rather give it one than pretend it doesn’t exist. Take out CHF 52.6 million in tariff refunds and On is a very healthy business with about a 67% gross margin, not a 72.6% one.
The bigger question is the next two years. On is betting it can be a running brand, a sneaker brand, a women’s apparel brand and a soccer brand at once, without losing the runners who made it.
So far, the run side is holding but let’s keep an eye on things moving forward.
Leave a Reply
You must be logged in to post a comment.